Key takeaways
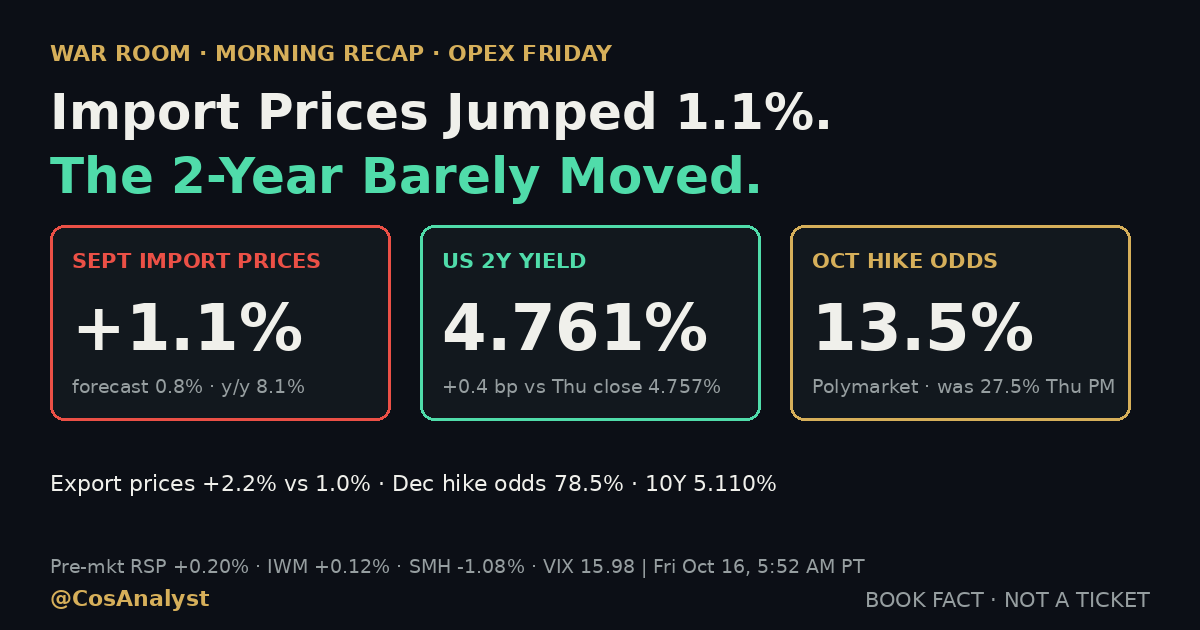
- September import prices rose 1.1% against a 0.8% forecast, and export prices rose 2.2% against 1.0%. Import prices are up 8.1% from a year ago, the largest 12-month gain since July 2022, and export prices are up 11.6% (BLS).
- The 2-year Treasury yield barely moved. It was 4.761% at about 5:52 AM PT, up 0.4 basis point from Thursday's close, after the third hot inflation print in three days.
- October Fed hike odds are 13.5% on Polymarket, December is 78.5%. Thursday afternoon October was 27.5%. The market kept the hike and left it in December.
- Friday is monthly options expiration, with industrial production at 6:15 AM PT and the cash open at 6:30 AM PT. Pre-market, SPY is +0.16%, QQQ is -0.21%, and chips are lagging again.
- Rotation is the story under the index. The equal-weight S&P 500 (RSP) and small caps (IWM) rallied 1.37% Thursday while the semiconductor ETF (SMH) fell 1.04%. SMH is -1.08% pre-market.
Core CPI ran hot Wednesday. Producer prices jumped 1.3% Thursday. This morning, September import prices rose 1.1% against a 0.8% forecast, the third hot inflation print in three days. The 2-year Treasury yield, the maturity most tied to Fed policy, is 4.761%, up 0.4 basis point from Thursday's close. The bond market has looked at three inflation surprises and mostly shrugged.
September import prices: the third hot inflation print in three days
The Bureau of Labor Statistics said U.S. import prices rose 1.1% in September, after a 0.5% rise in August. The 12-month gain is 8.1%, the largest since the index rose 8.8% for the year ended July 2022. Fuel did a lot of it: import fuel prices rose 4.8% in September, and nonfuel import prices rose 0.7% and have not declined on a monthly basis since August 2025. Export prices rose 2.2%, the second large monthly gain in a row, with agricultural export prices up 2.6%, the largest monthly rise since November 2022.
| Fri Oct 16 data (Sept unless noted) | Actual | Forecast | Prior (revised) |
|---|---|---|---|
| Import prices m/m | +1.1% | 0.8% | 0.5% (was 0.7%) |
| Import prices y/y | 8.1% | n/a | 6.7% |
| Export prices m/m | +2.2% | 1.0% | 1.2% (was 0.6%) |
| Export prices y/y | 11.6% | n/a | 9.3% |
| NY Fed Services Activity (Oct) | -20.7 | n/a | -8.7 |
Actuals from the BLS import and export price release (8:30 AM ET) and the New York Fed; forecasts and priors from the TradingView economic calendar. The August import-price gain was revised down to 0.5% from 0.7%, and the August export-price gain was revised up to 1.2% from 0.6%.
The week now reads as a run of upside surprises. Core CPI came in a tenth above consensus on Wednesday. PPI rose 1.3% against 0.5% on Thursday, the biggest monthly gain since March 2022, as we covered in our PPI morning note and Thursday close recap. Today's import and export numbers say the pressure is also showing up at the border. Growth signals are mixed: the New York Fed's services activity index fell to -20.7 in October from -8.7. Inflation up and growth soft is the stagflation framing, and for now the tape is not pricing it.
The 2-year yield barely moves
Here is the part that matters for pricing. The 2-year yield was 4.761% at about 5:52 AM PT, up 0.4 basis point from Thursday's 4.757% close. Wednesday it hit 4.95% intraday and closed near 4.806%, so the front end is still roughly 4 to 5 basis points under Wednesday's close and about 19 basis points under that spike. The 10-year yield is 5.110%, up 3.1 basis points from Thursday's 5.079% close and still above 5%. The gap between the two is about 35 basis points.
Our overnight Warsh note set two markers for the 2-year: back above 4.81% would mean the front end is rejecting the patient read, and under 4.75% would keep it alive. The 2-year is 4.761%, between the two. A hot print that cannot push the 2-year decisively higher is the market saying the next move is about timing, not direction.
Elsewhere the dollar index is 101.784, down 0.22%. $WTI is $95.77, down 2.25%, after Thursday's rally. Gold is $4,172.53, and Bitcoin (Bitstamp) is $81,951. The VIX is 15.98, under Thursday's 16.46 close. Here is our read, not a certainty: with $WTI giving back about $2 this morning, the energy part of the import-price story is not getting a second leg from crude today.
Fed rate hike odds for December: the hike moved, it did not leave
Polymarket prices a 25 basis point hike at the Oct 27-28 meeting at 13.5% as of 5:52 AM PT, with no change at 86.5%. The path: 27.5% on Thursday afternoon, 12.5% at 1:02 AM PT after Fed Chair Kevin Warsh's Thursday night appearance, and 13.5% now. That is a hold that survived a third hot print. For December, a 25 basis point hike is 78.5%, no change is 18.5%, and a 50 basis point hike is 3.25%. The same market that priced a September inflation wave did not pull the hike forward. It kept it in December.
Our overnight note asked a specific question: if import prices came in hot, would October odds climb back toward Thursday's 27.5%, or hold near 12.5%? So far they have held. That is the market choosing Warsh's tone over the data, and it is the main thing that would change if the 2-year breaks higher. We explain how we read these odds in our October and December hike odds note.
Stocks pre-market: flat to firm, with the Nasdaq lagging again
| Pre-market, Fri Oct 16 | Last | Change vs Thu close | Thu close |
|---|---|---|---|
| SPY | 773.03 | +0.16% | 771.79 |
| QQQ | 726.44 | -0.21% | 728.00 |
| IWM | 275.41 | +0.12% | 275.08 |
| RSP (equal weight) | 215.44 | +0.20% | 215.00 |
| SMH | 552.80 | -1.08% | 558.84 |
| S&P 500 futures (ES) | 7,800.75 | +0.13% | vs settle |
| Nasdaq-100 futures (NQ) | 30,067.25 | -0.25% | vs settle |
| Russell 2000 futures (RTY) | 2,784.6 | +0.10% | vs settle |
| VIX | 15.98 | -2.92% | 16.46 |
TradingView marks at about 5:52 AM PT / 8:52 AM ET. ETF and stock changes are pre-market versus Thursday's close; futures are versus the prior settle.
The shape is the same as the past two sessions. S&P 500 futures are up a little, Nasdaq-100 futures are down a little, and the weakness is concentrated in chips. A third hot print did not change that.
Rotation: equal-weight and small caps against chips
Thursday's rally was broad, not top-heavy. RSP and IWM both gained 1.37%, health care (XLV) gained 1.86%, consumer discretionary (XLY) gained 1.71% and financials (XLF) gained 1.38%. Against that, technology (XLK) fell 0.65%, SMH fell 1.04% and energy (XLE) fell 1.58%. This morning the equal-weight and small-cap trade is holding: RSP is +0.20% and IWM is +0.12%, while SMH is -1.08% and XLK is -0.19%. XLE is +0.77%, a bounce after Thursday's drop.
Chip names are soft again. Micron (MU) is -2.34% pre-market and Nvidia (NVDA) is -0.21%, with the AI-infrastructure complex also pricing debt worries around CoreWeave, per Stocktwits. The question for the equal-weight S&P 500 is whether a rotation that worked on a day of falling yields can hold on a day when the 10-year is back at 5.110%.
Movers: Tesla Roadster stock jumps, Apple-Meta AI lifts AAPL, Netflix and Travelers fall
| Stock, pre-market | Last | Change vs Thu close | Catalyst |
|---|---|---|---|
| TSLA | 373.77 | +3.13% | New Roadster unveiled as a flying car with SpaceX-style thrusters |
| AAPL | 347.73 | +1.68% | Apple-Meta AI collaboration, China AI approval |
| META | 738.58 | +0.25% | Apple partnership read-through |
| NFLX | 70.03 | -3.56% | Peter Rice named chief content officer |
| TRV | 373.99 | -2.58% | Q3 results this morning |
TradingView pre-market marks; catalysts from Reuters, GuruFocus, dpa-AFX, Benzinga, Stocktwits, Dow Jones and company releases via TradingView news.
Tesla is +3.13% at $373.77 after unveiling a new Roadster billed as a flying car, with SpaceX-style thrusters, according to Reuters, dpa-AFX and GuruFocus headlines. Barron's ran a headline asking whether even a flying car can lift tech stock gloom, which is the tone of this tape. Tesla reports earnings Oct 21, after the close.
Apple is +1.68% at $347.73 on two stories. Apple and Meta are collaborating to run Meta's Muse AI models on the Mac (Stocktwits, Seeking Alpha), and TradingView lists a China approval for Apple's AI. Wedbush's Dan Ives said the Apple-Meta AI partnership could help unlock $75 per share in AI value for Apple (Benzinga). That is an analyst estimate, not a company figure. Meta is +0.25%.
Netflix is -3.56% at $70.03. It named former Disney executive Peter Rice chief content officer, to succeed Bela Bajaria on Oct 26 (Dow Jones), amid questions about viewer engagement and growth (WSJ, Barron's headlines). Netflix reports Oct 20, after the close.
Travelers (TRV) is -2.58% at $373.99 after Thursday's +1.61% close at $383.89. The company reported third-quarter net income of $1.917 billion, or $9.04 per diluted share, and core income of $1.947 billion, or $9.18 per share, up from $8.14 a year ago. Benzinga put consensus at $7.42, so core earnings beat by a wide margin. The combined ratio was 86.8% against 87.3% a year ago, net written premiums were flat at $11.48 billion, and the company said higher catastrophe losses partly offset higher reserve releases and investment income. We have not confirmed why shares are lower pre-market despite the beat.
Options expiration October 16: what to watch today
- Fri Oct 16, 6:15 AM PT (9:15 AM ET): industrial production (forecast +0.4%, prior 0.0%), manufacturing production (forecast +0.3%) and capacity utilization (forecast 76.5%).
- Fri Oct 16, 6:30 AM PT (9:30 AM ET): the cash open. It is also monthly options expiration, and standard monthly SPX options are AM-settled off the opening prints. For the mechanics, see our explainers on positive versus negative gamma and gamma exposure.
- Fri Oct 16, 10:00 AM PT (1:00 PM ET): Baker Hughes rig count, a $WTI catalyst.
- Fri Oct 16, 11:00 AM PT (2:00 PM ET): monthly budget statement (forecast -$29B, prior -$167B).
- Fri Oct 16, 12:30 PM PT (3:30 PM ET): CFTC Commitments of Traders for the week of Oct 13.
- Fri Oct 16, 1:00 PM PT (4:00 PM ET): TIC long-term flows (forecast $75.2B, prior -$27.9B).
- Fri Oct 16, 3:00 PM PT (6:00 PM ET): Fed's Goolsbee speaks.
- Next week: Netflix earnings Tue Oct 20, Tesla earnings Wed Oct 21, jobless claims Thu Oct 22 at 5:30 AM PT, and the Oct 27-28 FOMC meeting.
Three ways today can go
- The 2-year stays near 4.761% and industrial production lands near forecast: the patient-Fed read survives a third hot print, October odds stay in the low teens, and the rotation into equal-weight and small caps has room to continue.
- The 2-year pushes back toward Wednesday's 4.806% close: the front end is saying a December hike needs more than a delay, and October odds can climb back toward Thursday's 27.5%. The first pressure point would be QQQ and SMH, which are already soft.
- Industrial production beats while the 10-year holds above 5%: it fits a resilient economy that can absorb a hike, supports December more than October, and keeps long yields the weak spot.
We do not know which of these wins. We know the questions: does the 2-year keep ignoring inflation, and does the breadth rally hold through the open and the expiration settlement.
FAQ
What did September import prices show?
U.S. import prices rose 1.1% in September against a 0.8% forecast, and export prices rose 2.2% against 1.0%, according to the BLS. Import prices are up 8.1% from a year ago, the largest 12-month gain since July 2022, and export prices are up 11.6%. The prior import-price reading for 12 months was revised to 6.7%, and August's monthly gain was revised down to 0.5% from 0.7%.
Why did the 2-year Treasury yield barely move after hot import prices?
The 2-year yield was 4.761% at about 5:52 AM PT, up only 0.4 basis point from Thursday's close. Our read is that traders have already moved their Fed expectations out to December after Warsh's Thursday night comments, so a third hot inflation print changed little about October. It is a read, not a confirmed cause, and the 10-year at 5.110% shows long bonds are less comfortable.
What are the Fed hike odds for December 2026?
Polymarket priced a 25 basis point hike at the December meeting at 78.5% as of 5:52 AM PT, with no change at 18.5%. The October hike is 13.5%, down from 27.5% on Thursday afternoon. The FOMC meets Oct 27-28.
What should traders watch on options expiration Friday, October 16?
Industrial production at 6:15 AM PT (forecast +0.4%), the cash open at 6:30 AM PT, when standard monthly SPX options settle off the opening prints, the Baker Hughes rig count at 10:00 AM PT, the CFTC report at 12:30 PM PT and Fed Goolsbee at 3:00 PM PT. The 2-year yield and the equal-weight S&P 500 against chips are the two cleanest reads on whether the tape is changing.
Follow the desk
Follow @CosAnalyst on X for the read on industrial production and today's expiration as they land. Join the free Telegram alerts channel, Free Index & BTC Trade Alerts. It posted no signals on Thursday, and sitting out when the setup is not there is part of the plan. Nothing there is financial advice.
BOOK FACT · NOT A TICKET. CosAnalyst research and analysis, not financial advice or a trade recommendation. Import and export price figures are from the Bureau of Labor Statistics U.S. Import and Export Price Indexes news release for September 2026 (USDL-26-1577, 8:30 AM ET, Oct 16). Forecasts, priors and the economic calendar are from TradingView. Quotes, pre-market marks, futures, yields, the dollar index, $WTI, gold, Bitcoin and VIX are TradingView marks at about 5:52 AM PT / 8:52 AM ET, Fri Oct 16, 2026, before the cash open. Thursday closes are TradingView daily closes. Fed odds are from the Polymarket gamma API as of about 5:52 AM PT, compared with Thursday afternoon and our overnight note. Travelers figures are from its third-quarter 2026 earnings release (Business Wire, Oct 16) and the consensus comparison is from Benzinga. Catalyst headlines are via TradingView news from Reuters, dpa-AFX, GuruFocus, Dow Jones, Benzinga, Stocktwits and Seeking Alpha; the $75 per share figure is a Wedbush estimate. FOMC dates are from federalreserve.gov. Prediction-market odds and market data change quickly.