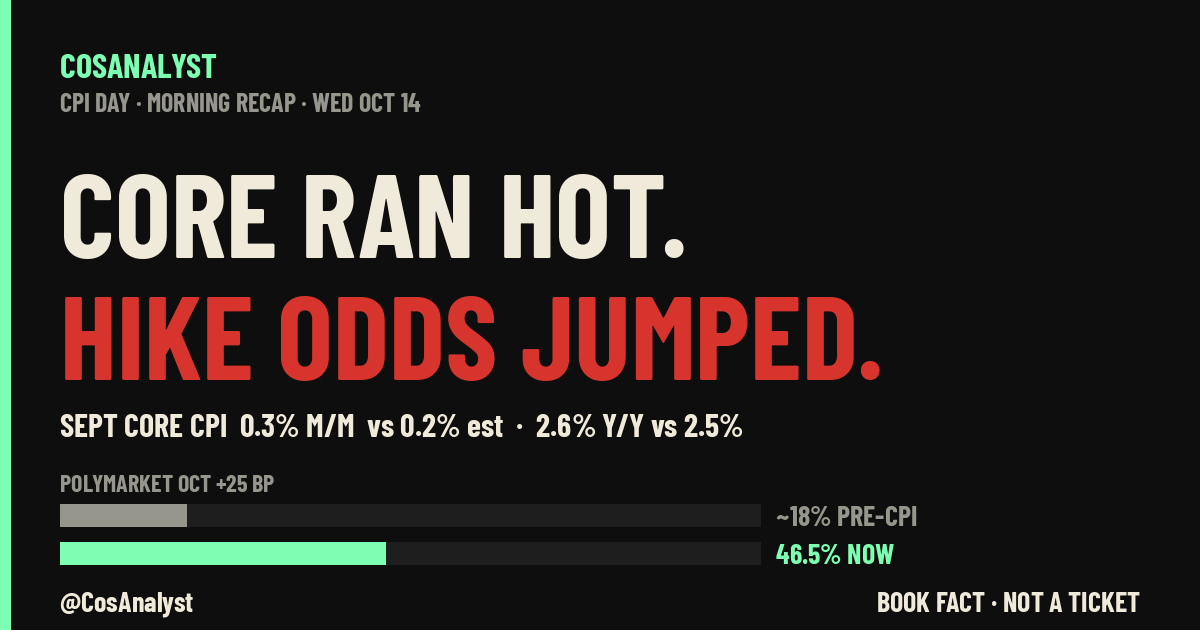
The short answer (as of the 4:00 PM ET close, Wed Oct 14, 2026): A hot core CPI reading, 2.6% year over year and 0.3% month over month against 2.5% and 0.2% expected, sparked a broad stock market selloff. SPY fell 1.08% to 769.60, QQQ fell 1.97% and IWM fell 1.93%. The VIX jumped 10.34% to 16.86. Chip stocks led the decline (SMH -3.98%) while defensive stocks rallied (XLV +2.53%, XLP +2.22%). Polymarket closed with a 30.5% chance of an October Fed hike, down from 33.5% at midday but far above about 17-18% before the print. PPI tomorrow at 8:30 AM ET is the next test.
For months, investors treated the Fed's warnings about inflation as background noise. On Wednesday they listened. One tenth of a percentage point on core CPI was enough to turn an October rate hike from a long shot into a live bet, and the market spent the rest of the session doing what markets do when they take a central bank at its word: selling the stocks that need cheap money and buying the ones that do not.
The damage was orderly but wide. The S&P 500 tracker SPY closed down 1.08% at 769.60, after trading between 766.71 and 776.30. The Nasdaq 100 tracker QQQ dropped 1.97% to 728.95, and small caps (IWM) fell 1.93% to 271.37. The VIX, Wall Street's fear gauge, rose 10.34% to 16.86 and closed near its session high. This was not panic. It was a repricing, and it had a clear shape.
Hot CPI, stock market selloff: what the print said
The headline was never the surprise. With $WTI near $95, everyone expected energy to keep headline inflation firm, and it did: 3.7% year over year against 3.6% expected, and 0.6% on the month, in line. The problem was core, the measure that strips out food and energy and the one the Fed watches most closely. Core CPI rose 2.6% year over year, up from 2.4% in August and a tenth above the 2.5% consensus, and 0.3% on the month against 0.2% expected. Our morning CPI breakdown walks through the components, from airfares to hotels.
| Measure | Actual | Consensus | Prior |
|---|---|---|---|
| CPI, year over year | 3.7% | 3.6% | 3.4% |
| CPI, month over month | 0.6% | 0.6% | 0.4% |
| Core CPI, year over year | 2.6% | 2.5% | 2.4% |
| Core CPI, month over month | 0.3% | 0.2% | 0.3% |
A tenth sounds small. It matters because it arrived when the Fed's next move was already a question of when, not whether, and because it pointed the wrong way for anyone hoping the energy shock would stay contained in gasoline prices.
Fed hike odds for October 2026: sticky, not settled
Before the report, Polymarket gave a 25 basis point hike at the Oct 27-28 meeting roughly 17-18%. The odds spiked after 8:30 AM ET, stood at 33.5% at midday and finished the day at 30.5%, with no change at 68.5%. The fade from midday is real, but the bigger fact is the level: the market now treats October as a meeting that could deliver a hike.
Further out, the bet is close to settled. Polymarket prices a 78.5% chance of a 25 basis point hike in December, and two hikes in 2026 is the favorite outcome at 64.5%. The open question is timing, and Thursday's data will push it one way or the other.
There is a lesson in how the day started. Ahead of the report, Polymarket's favorite outcome for core CPI was 2.4%, softer than economists' 2.5%. The actual 2.6% was on the far side of both. Prediction markets are useful for reading the crowd, but the crowd can lean the wrong way on the print, and on Wednesday it did.
Why tech stocks fell today
Higher expected rates hit hardest where valuations rest on profits far in the future. That is the semiconductor and AI complex. SMH, the chip ETF, fell 3.98% and the technology sector fund XLK lost 2.98%. AMD dropped 5.73%, Micron 4.10% and Nvidia 3.16%. Among the megacaps, Meta fell 3.27%. Apple was the exception, up 0.50%, a sign that investors were selling rate sensitivity more than they were selling big tech as a group.
Treasury yields told a quieter story than stocks. The 10-year yield actually closed down 2.3 basis points at 5.194%, easing off a midday spike, while the dollar index (DXY) rose 0.32% to 102.542. Bitcoin fell 1.62% to 81,723 and gold lost 1.47% to 4,099.5, so even the usual hedges offered no shelter. High-yield credit (HYG) slipped 0.36%, moving with stocks rather than against them.
Defensive stocks took the bid
The other side of the trade was textbook. Health care (XLV) rose 2.53% and consumer staples (XLP) gained 2.22%, the two best sectors on the board. Energy (XLE) added 0.64% as $WTI rose 1.00% to $95.08, which is the same oil price that keeps headline inflation hot. Investors rotated toward companies whose earnings do not depend on cheap financing or long growth runways.
| Leaders | Change | Laggards | Change |
|---|---|---|---|
| XLV (health care) | +2.53% | SMH (semiconductors) | -3.98% |
| XLP (staples) | +2.22% | XLK (technology) | -2.98% |
| XLE (energy) | +0.64% | AMD | -5.73% |
Banks split on earnings day
Bank earnings added a second storyline. Bank of America fell 4.76% after its third-quarter profit was hit by a $1.2 billion regulatory reserve, according to Reuters and CNBC. Morgan Stanley lost 2.73%. JPMorgan went the other way, up 1.16%, and BlackRock rose 0.74%. In a market repricing rates, the dispersion is the point: investors were sorting balance sheets one by one rather than buying or selling the group.
PPI tomorrow: the next test
Wednesday settled the question of whether the market would take hot core seriously. Thursday asks whether it was a one-month scare or a trend. At 8:30 AM ET the Producer Price Index lands with retail sales, jobless claims and the Empire State and Philadelphia Fed manufacturing surveys. PPI measures prices further up the supply chain, so a hot reading would suggest more pressure still on its way to consumers.
- Thu Oct 15, 8:30 AM ET / 5:30 AM PT: PPI, retail sales, initial jobless claims, Empire State and Philly Fed.
- Thu Oct 15, about 11:30 PM ET / 8:30 PM PT: Fed Chair Kevin Warsh speaks.
- Fri Oct 16: Monthly options expiration.
- Oct 27-28: FOMC meeting.
How we read the scenarios
- Hot PPI and firm retail sales: the October hike case strengthens and odds likely push back above Wednesday's midday high. Growth stocks and chips stay under the most pressure.
- Soft PPI or weak retail sales: Wednesday starts to look like a one-tenth scare, and some of the rotation into defensives could unwind.
- Mixed data: Warsh gets the last word Thursday night, after the cash close, heading into Friday's options expiration.
Our read: the market did not decide the Fed will hike in October. It decided the Fed means what it says. That is a different market from the one that opened the week, and it will be tested every morning the data arrives.
FAQ
Why did the stock market fall today, Oct 14, 2026?
September core CPI came in hot at 2.6% year over year and 0.3% month over month, a tenth above consensus on both, raising the odds of an October Fed hike. SPY fell 1.08%, QQQ 1.97% and IWM 1.93%.
Why did tech stocks fall today?
Higher expected interest rates weigh most on growth stocks whose value depends on future profits. SMH fell 3.98% and XLK 2.98%, with AMD down 5.73%, Micron 4.10% and Nvidia 3.16%.
What are the Fed hike odds for October 2026?
At Wednesday's close, Polymarket priced a 30.5% chance of a 25 basis point hike at the Oct 27-28 meeting, against 68.5% for no change. Before CPI the hike odds were about 17-18%. December hike odds were 78.5%.
Which stocks went up after the hot CPI report?
Defensive stocks. Health care (XLV) rose 2.53%, consumer staples (XLP) 2.22% and energy (XLE) 0.64%. JPMorgan (+1.16%), BlackRock (+0.74%) and Apple (+0.50%) also finished higher.
Why did Bank of America stock fall?
Bank of America fell 4.76% after its third-quarter profit was hit by a $1.2 billion regulatory reserve, according to Reuters and CNBC.
When is PPI tomorrow?
The September Producer Price Index is released Thursday Oct 15, 2026 at 8:30 AM ET, alongside retail sales, jobless claims, Empire State and Philly Fed. Fed Chair Warsh speaks around 11:30 PM ET that night.
Follow the desk
Follow @CosAnalyst on X for the read on PPI, retail sales and Warsh as they land. Join the free Cos Analyst Signals channel on Telegram for research notes and posted receipts, wins and losses: https://t.me/CosAnalystSignals. Nothing there is financial advice.
BOOK FACT · NOT A TICKET. CosAnalyst research and analysis, not financial advice or a trade recommendation. Closing quotes, sectors, yields, dollar, $WTI, bitcoin and gold from TradingView, cross-checked against SIP last prints. CPI data from the BLS via the TradingView economic calendar, with consensus and same-day market coverage from Reuters via Yahoo Finance. Bank of America reserve detail from Reuters and CNBC. Fed decision and 2026 hike-count odds from Polymarket. Prediction-market odds can change quickly.