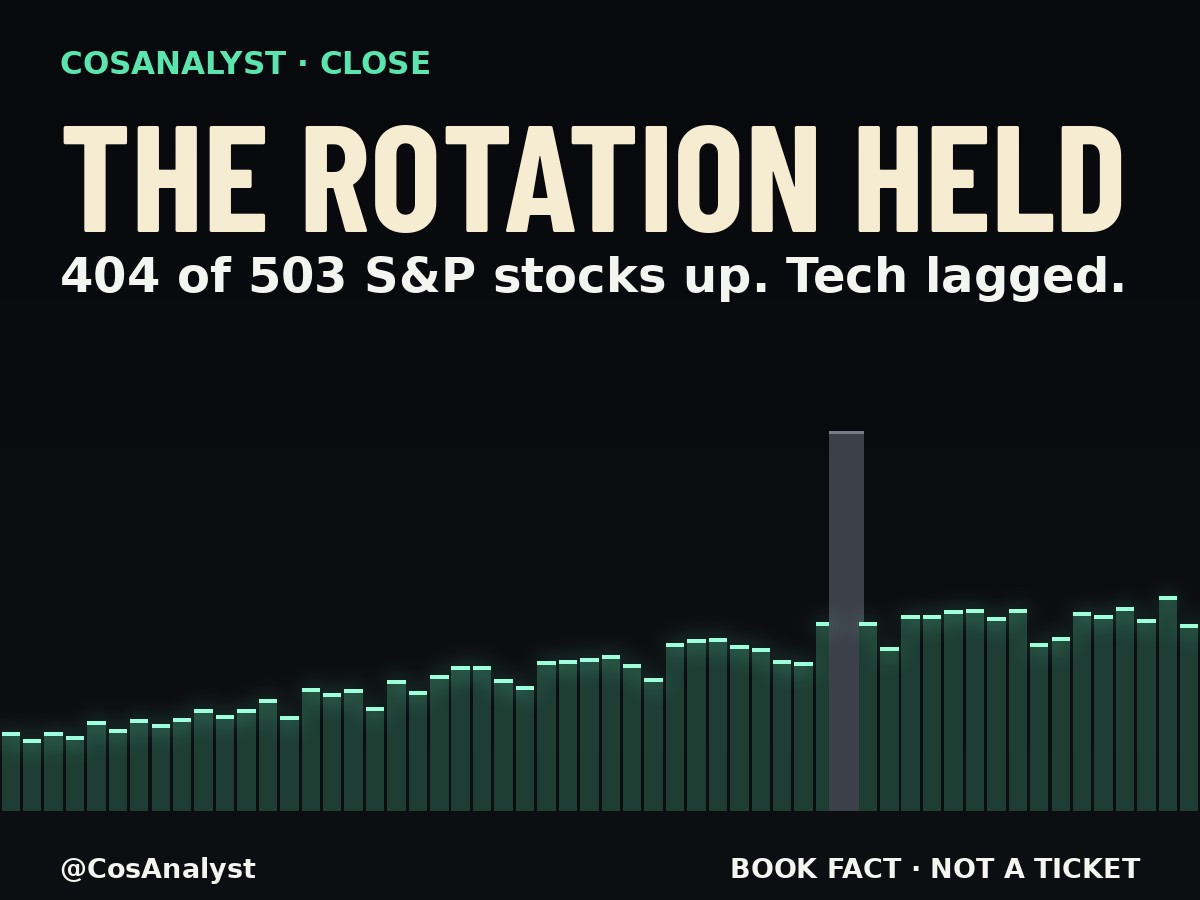
The rotation held to the bell. Monday was a narrow AI bounce with most of the market falling. Tuesday was the mirror image: 404 of 503 S&P 500 stocks rose, the Dow jumped 530 points, and tech was the only sector in the red.
The board
- Dow 52,495.88, +1.02% (+530).
- S&P 500 7,712.57, +0.28%.
- Nasdaq Composite 26,424.82, -0.02%.
- VIX 17.31, -6.1%.
Breadth: the whole field moved
- 404 of 503 S&P 500 stocks up.
- $RSP +1.15% vs $SPY +0.34%. The average stock beat the index by a wide margin.
- $IWM +1.66% led the majors.
Health care $XLV +2.37% topped the sector board. Tech $XLK -0.28% was the only sector down, with $SMH -0.38%. Chip equipment fell into earnings: $LRCX -3.2%, $KLAC -2.8%. Megacaps lagged: $META -1.59%, $GOOGL -1.13%, $AAPL -1.00%.
Earnings movers
- Equifax $EFX +11.3%: Q3 adjusted EPS $2.26 vs $2.20 expected, though it trimmed revenue guidance.
- Hasbro $HAS +11.2%.
- 3M $MMM +5.8%, helped by an Amazon data-center deal.
- Northrop Grumman $NOC +4.6%.
- Eli Lilly $LLY +3.5%.
- General Motors $GM -6.8%: its forecast disappointed despite a $20B buyback.
- GE Aerospace $GE -3.7%: free cash flow missed.
After hours
- Netflix $NFLX beat Q3 but cut Q4 guidance, and the stock fell late.
- SpaceX reported a profit as revenue doubled.
- Super Micro $SMCI raised its outlook.
Rates, oil and crypto
The 10-year Treasury yield fell 2.7 bp to 5.115%, and 2s10s sits near +33.5 bp in a bull flattener. $WTI settled at $98.23, -0.31%, and Brent at $108.79, on US-Iran talk hopes that remain unconfirmed. $BTC is $82,650.
Housing keeps sinking
September housing starts came in at a 1.221 million rate against about 1.31 million expected. Pending home sales fell 7.3% month over month. With Monday's NAHB index at 29, that is three weak housing reads in two days, and part of why yields eased.
Fed odds
Polymarket prices an October hike at 13.5% and a December hike at 77.5%. The CME FedWatch October-hike figure of 17.2% is Monday's read, not re-verified today. Market odds are not a forecast.
Positioning: premarket gamma estimate
These flips are a premarket desk estimate, not refreshed intraday. SPY flip: about 766.1. QQQ flip: about 720.6. $QQQ closed below it at 717.63, which fits a day when the money left the AI trade and went everywhere else.
What to watch
- 1. Tonight and Wednesday open: how the market digests the Netflix guidance cut.
- 2. Wednesday: whether breadth survives as megacap and chip earnings put AI back in focus, and whether $QQQ can get back above its estimated flip.
- 3. Housing and yields: whether weak data keeps pulling the 10-year lower.
Takeaway
Monday was AI without the market. Tuesday was the market without AI, and it held all the way to the close. The test now is whether the rotation survives Netflix's guidance cut and the megacap reports ahead.
Follow @CosAnalyst on X for the morning board and the close. For our free research signals as they land, losses included, join the Cos Analyst Signals channel on Telegram: https://t.me/CosAnalystSignals.
BOOK FACT · NOT A TICKET. CosAnalyst research. Not financial advice. Figures per the Trading Chief of Staff close desk report, Tue Oct 20, 2026. The US-Iran talk reports are unconfirmed. CME FedWatch 17.2% is Monday's figure, not re-verified today. Dealer gamma flips are a premarket desk estimate, not refreshed intraday.